Showing posts with label Core Tier 1. Show all posts

Saturday, 16 March 2013

Credit - Dumb buffers

"When the weather changes, nobody believes the laws of physics have changed. Similarly, I don't believe that when the stock market goes into terrible gyrations its rules have changed."
- Benoit Mandelbrot 

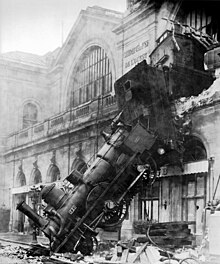
A buffer is a part of the buffers-and-chain coupling system used on the railway systems of many countries, among them most of those in Europe, for attaching railway vehicles to one another. Buffers in the very earliest days of railways were rigid (dumb buffers). 
Cross section of volute spring buffer

You might wonder where we might be going with this week's railway analogy, but, looking at the recent senate hearings following last year JP Morgan's 6 billion dollar losses, discussions surrounding banks and equity capital have resurfaced as of late. Arguably one of the most pertinent read we have come across was from Bloomberg's editors - JPMorgan’s $6 Billion Loss Shouldn’t Be a National Matter:
"To make the whole system more resilient, banks need to get a larger share of their funding in the form of equity from shareholders, as opposed to loans from depositors and other creditors. We have advocated $1 in equity for each $5 in assets, a level that would absorb a 20 percent drop in the value of a bank’s investments, compared with JPMorgan’s 3.1 percent. The latest global banking rules require only $1 in equity for each $33 in assets, and use a lenient approach for measuring the ratio.
Higher equity requirements reduce taxpayer support to banks in a different way, by making them less likely to require bailouts. The added discipline would also put natural pressure on banks to shrink: Once shareholders fully realized how poorly the largest banks perform in the absence of subsidies, they would have more incentive to demand that they be broken up into smaller, more profitable units." - source Bloomberg

Dumb buffers were the source of many staff accidents and damaged loads and vehicles. The Board of Trade required all new construction in England and Wales from 1889 to have spring buffers, but in Scotland the railway companies continued to accept new wagons with dumb buffers until 1 October 1903. From 31 December 1913 all dumb buffered vehicles were banned from the main line, but the Scottish owners gained an extension to 1915. In fact, the disruption of the Great War meant that dumb buffers persisted in Scotland until at least 1920-21. 

One can argue that the latest global banking rules requiring only $1 in equity for each $33 in assets is akin to the famous dumb buffers that plagued Scottish railways for an extended period of time, which might be leading to many "derailments" for banks in particular and for the economy in general as witnessed with the financial crisis of 2008:

Similar to Bloomberg editors and Simon Johnson, MIT professor and former chief economist at the IMF, we have long advocated larger equity buffers for banks in order to reduce the systemic risk banks pose to the real economy as a whole. Back in October 2011, in relation to discussions surrounding Capital Regulation, contrary to many beliefs, we argued as well that Bank Equity is not expensive. It is a myth. A study realized by Stanford University by Anat R. Admati is a must read. a summary of the presentation made to the Bank of England by the co-author is available here:
"Fallacies, Irrelevant Facts, and Myths in the Discussion of Capital Regulation: Why Bank Equity is Not Expensive"

A summary of a presentation to the Bank of England is available below which highlights Professor's Admati's key findings.
http://www.bankofengland.co.uk/publications/events/ccbs_workshop2011/presentation_admati.pdf

Some countries such as Denmark have started asking for higher extra capital. For instance, Denmark's systematically important financial institutions will have to hold 2.5% to 5% of extra capital as recommended by Denmark's Sifi committee. Its recommendations will have to be passed into law by the Danish parliament.

While the European Union us trying to press ahead with global banks standards by March 22nd, if the measures are not in place by month end, it would mean additional delays in implementing the January 2014 target for Basel III accord, which could potentially shorten the transition period and put some additional strain on lenders to adjust by the start of 2014 or delay the implementation until January 2015.

In this week conversation, we would like to focus our attention to this very important subject of bank regulation and capital adequacy, given both the European Union and the US have struggled to agree on legislation to apply the international standards on capital, known as Basel III, which were published in 2010 in conjunction with the Dodd-Frank act, following the demise of Lehman Brothers Holdings Inc.

So far, the Basel rules negotiations also have been stalled on how much additional capital should be required for systemically important financial institutions as reported by Rebecca Christie and Caroline Connan in their Bloomberg article from the 26th of February entitled - Barnier Says EU Needs Basel Deal to Lift Uncertainty for Banks:
"Lawmakers are pushing the EU to include in the capital rules a requirement for country-by-country reports on profits, losses and taxes, according to the document. Nations have been reluctant to expand the scope of the capital rules, preferring to tackle the topic in separate accounting legislation.
The Basel Committee on Banking Supervision brings together banking regulators from 27 nations including to the U.S., U.K., and China to coordinate their prudential rule-making.
The Basel III measures, which must be written into national laws, would more than triple the core capital lenders must hold and set standards for how lenders should manage risks. Representatives of Karas and the Irish presidency in Brussels declined to comment on the paper." - source Bloomberg.

On top of that, regulators from the Basel Group have clearly put Bank's debt addiction on scrutiny this year as reported by Ben Moshinsky and Jim Brunsden in Bloomberg on the 12 th of March - Bank's Debt Addiction Said to Face Scrutiny at Basel Meetings:
"Regulators are preparing to fight lenders over the details of the so-called leverage ratio as they seek to toughen rules on the minimum amount of capital they must use to back their investments. The Basel group, which brings together supervisors from 27 nations, will meet in the Swiss city tomorrow, according to the people, who asked not to be identified because the meetings are confidential.
 Concerns over how banks calculate reserves has led U.K. bank regulator Adair Turner and U.S. Federal Deposit Insurance Corp. board member Jeremiah Norton to call for tougher leverage ratios. Global supervisors in 2010 included a draft leverage ratio in an overhaul of rules, known as Basel III, drawn up in response to the financial crisis that followed the collapse of Lehman Brothers Holdings Inc.
“Early on, banks did not see it as such a big danger, or as a priority for lobbying, because it looked less likely to be implemented in the EU than other parts of Basel III,” Philippe Lamberts, the lawmaker leading the work on the Basel III rules for the European Parliament’s Green group, said in a telephone interview.
Leverage ratios force banks to hold capital equivalent to a percentage of the value of their assets. Such measures are simpler than standard capital requirements as they don’t give banks any scope to take into account the riskiness of their investments when calculating the reserves they must hold." - source Bloomberg

Back in September 2011, we quoted Dr Jochen Felsenheimer from asset management company "assénagon" now called "XAIA", we would like to quote him again looking at the current context:
"Banks employ too much debt, because they know that they will ultimately be bailed out. Governments do exactly the same thing. 

Banks have fought bitterly against increasing equity buffers which is the cheapest and easiest way to recapitalize banks. Why? Because allowing high payouts to shareholders, namely bank employees in many cases, allows financial institutions to raise their leverage: "Focus on ROE is also a reason bankers find hybrid securities, such as debt that converts to equity under some conditions, more attractive than equity." - Anat R. Admati.

For instance, since 2009, banks have indeed been very creative in the methodology used to beef up their Core Tier 1 ratio using a new generation of Hybrids securities called CoCo (Contingent Convertible Capital). CoCos, convert to equity or are written off once an issuer’s capital ratios fall below a preset level. This market for these new securities, already amounts to +10 billion dollars. This contingent convertible security pays a higher coupon and automatically convert into equities or suffer a full or partial write-down when the bank's capital ratio falls below a pre-defined trigger. 

The beauty for the issuer is that the CoCo automatically boosts its Core Tier 1 capital ratio in times of stress rather than being forced into a dilutive right issue during difficult market conditions. Owning a CoCo, according to a recent BNP Paribas note is very similar to selling a Down-and-In put option on the issuing
bank’s shares with a knock-in barrier linked to a balance sheet capital ratio as opposed to stock price level.
The issuing bank is effectively buying skew and convexity (crash protection) from the investor, who is exposing himself to losses in stress scenarios. 

It is not a free lunch although a coupon in the region of 7% to 8% is outright appealing in this low rate / low yield environment.

The benefits of such transactions for the issuer of CoCo notes is that not only it enables the issuer to maintain a particular minimum capital level, it also pleases the regulator and allows issuers which have been previously bailed out in Europe, to continue repayment of the aid received. For instance, KBC bank issued in January 1 billion dollar worth of CoCos, allowing them to continue the repayment schedule on time and, following a stress test, the National Bank of Belgium had required an additional 2 billion euros of Core Tier 1 capital to be raised. KBC completed in December 2012 a 1.25 billion euro equity offering and 750 million euros worth of CoCos.
While Europe is falling behind in relation to the implementation of Basel III, Switzerland has started implementing it as of January 2013 as indicated in a recent note by BNP Paribas on KBC's specific CoCo from January 2013:
"It is worth pointing out that due to the implementation of Basel 3 in Switzerland starting January 2013 as planned (as opposed to the delay in Basel 3 implementation in Europe, due to delay in completion of CRD4), the relevant ratio in ascertaining the likelihood of trigger is now the Core Equity Tier 1, rather than Core Tier 1 as it was under Basel 2.5. While this comes as no surprise and should have been fully expected it does make quite a bit of difference. For instance, at its Q3 12 UBS reported Basel 2.5 Core Tier 1 ratio of 18.1%, whereas the pro-forma phased in Basel 3 CET1 ratio was 13.6%." - source BNP Paribas

The fixation bankers have with equity buffers mean that they prefer issuing hybrids securities such as CoCos rather than equity in order to maintain their leverage and generate ROE. As indicated by Dr Jochen Felsenheimer, in case of trouble, the insurer is the taxpayer. CoCos are deemed to be "capital" and automatically improve the capital ratios, pleasing regulators in the process, and avoiding an automatic dilution of existing shareholders via capital increases through right issues. They are not equivalent to "equity", they are debt instruments, paying no doubt, a higher coupon, given the risk taken by the low subordination and risk of capital wipe-out faced by the bondholders.

As a reminder, under the draft Basel III plan in 2010, banks would have to hold so-called Tier 1 capital equivalent to 3 percent of their assets, so capping a lender’s debt at no more than 33 times those reserves, which, we think is way too low.

Last week events surrounding German Bank Commerzbank's capital increase is a reminder of not only the lack of sufficient equity buffer in the banking space but is also indicative of the material impact internal models of RWA (Risks Weighted Assets) can have to boost capital ratios as highlighted again in Bloomberg's article from the 12th of March - Bank's Debt Addiction Said to Face Scrutiny at Basel Meetings:
"The temptation for banks to boost their reserves through changes to risk calculations, rather than real steps to raise capital, could be countered by a strong leverage ratio, said Lamberts, the European lawmaker. One example of this is how German lender Commerzbank AG sought to meet EU capital rules in part by adjusting its risk calculations, rather than simply raising fresh reserves, Lamberts said.
“Details that are coming to light about how banks misuse their internal models, for example when Commerzbank said it would make up half of a capital shortfall through changes to its models, show the need for this kind of rule,” he said.
Commerzbank was one of more than 60 lenders told by the European Banking Authority to hold capital equivalent to 9 percent of its risk-weighted assets." - source Bloomberg

On March 2013, Commerzbank AG, Germany's second largest bank announced it would sell 2.5 billion euros of shares to repay the government and insurer Allianz SE. Commerzbank received a 18.2 billion euros bailout in 2009 and the German government had owned 25% of the bank prior to the announcement.

Of course the 15% dilution announcement led to the share sliding 14% in Frankfurt on the 13th of March - source Bloomberg:
 The share declined 14% valuing the bank at around 7 billion euros.

Commerzbank's shares, the intraday proverbial "sucker punch" - source Bloomberg:
This news made us chuckle given that the CEO Martin Blessing, will be using the capital raised to repay 1.6 billion euros owned to the government and 750 million euros to German insurer Allianz, as well as increasing its Core Tier 1 capital to 8.6% under full Basel III capital from 7.6%. 


Why did we chuckle, you might ask? Well, because Commerzbank's largest shareholder SoFFin (Special Financial Market Stabilization Fund), converted already its silent participation in June 2012 to approximately 58.85 million Commerzbank shares,  increasing in effect the capital of Commerzbank to maintain its equity interest ratio in Commerzbank to 25% plus one share. With the 15% dilution, this participation will be now diluted to 20%, meaning in effect a loss for the German taxpayers.
Oh well...

But this painful adjustment for Commerzbank will not be the last one, given we have already established the link between credit and shipping and in particular the exposure of German's second largest bank to shipping woes back in August 2012:
"Commerzbank – the world’s second-biggest provider of ship finance, and reluctant owner of a flotilla of foreclosed ships – said it is shutting down its €20bn (£15.7bn) ship funding operations entirely to “minimise risk and capital lock-up” under tougher EU banking rules."

In April in 2011, in our conversation "Shipping is a leading credit indicator", we indicated:
"Commerzbank’s 2008 takeover of Dresdner Bank AG increased its stake in shipping lender Deutsche Schiffsbank to 92 percent, doubling the size of its maritime-loan portfolio, just before the industry entered its biggest crisis since World War II." - source Bloomberg.

One can wonder what will be the recovery value for its maritime-loan portfolio looking at the boom and bust which occurred in the shipping space - source Bloomberg:
"The marine shipping industry is highly cyclical and susceptible to periods of boom and bust. Cycles are driven by overbuilding during times of growth to take advantage of strong markets. Shipping companies do not have enough lead time to alter orders when economic activity begins to slow, which has a significant effect on freight rates." - source Bloomberg.

Not only have overbuilding occurred due to cheap credit that fuelled an epic bubble in the Baltic Dry Index, but, the on-going decline on vessel prices, will no doubt exert additional pressure on recovery values for Commerzbank's loan book:
"Prices of seaborne vessels have crashed since peaking in 4Q08 and have been steadily declining since 4Q09, as excess capacity slowed the new build backlog, along with cheaper builds in China and tight credit markets. Chinese shipbuilders have been using price in attempt to win market share. Price pressure has come on less sophisticated dry-bulk ships relative to LNG tankers." - source Bloomberg


On the subject of banks capital shortfalls and the need to deleverage, and RWAs in particular, Nomura's note from the 11th of March 2013 entitled EU banks - Reconciling weak macro with momentum made some interesting points:

"To illustrate the point on headline capital ratios, the last published EBA Basel 3 monitoring exercise showed that at end-2011, European banks required EUR 225bn of equity capital to meet the minimum CET1 requirement of 7.0% of RWAs (inclusive of GSIB buffers where required). The report implied that the risk-weighted capital ratio rather than the unweighted leverage ratio was more of a bind on banks’ capital needs (given that the bar for unweighted leverage at 3.0% is set rather low, in our view). While we do not expect an official update on the 2012 capital position before September 2013, the EBA did separately disclose that as a result of capital raised for the 2012 stress test as well as other capital measures, European banks increased their capital positions by more than EUR 200bn in 1H 2012 (mostly through measures that directly increase capital rather than reduced assets). Based on the 2011 run-rate of net profit, in 2H 2012 around another EUR 40bn could have been added to banks’ capital bases.
Given that some banks will choose to build additional capital buffers, we do not expect the next monitoring exercise to show zero capital shortfall at end-2012 (several of the large often wholesale banks such as Deutsche Bank still had a gap at end-2012). However, we expect the reported capital shortfall to be substantially reduced for end-2012.
We are aware in 2013 that regulators are looking to improve harmonisation of the measurement of RWAs, moving away from internal models. In some cases, the banks have been well prepared (such as in Sweden) while in others it will delay the timeline to full Basel 3 compliance (such as in the UK). In general, we find that it is the wholesale banks with the lowest RWA/total asset ratios that might have the most need for additional capital actions or balance sheet shrinkage to meet regulatory goals. 
However, our main concerns for the banks are less about the measurement of RWAs and more about the fact that in some economies (such as Spain), the historical cost carrying value of banks’ assets is too high compared with their market value considering the fall in real estate prices in those economies. These unrecognised bad assets (along with deteriorating GDP and rising unemployment) require banks to divert profits to loan loss reserves rather than new lending." - source Nomura.


Moving back to our discussion around bank regulation and capital adequacy, we need to ask ourselves what have been accomplished since the demise of Lehman in 2008? Not enough, as indicated by the Bloomberg editors on the 10th of March in their article - Getting the Banks Around the World to Play by the Same Rules:
"Since that 2008 pact, progress has been made on the road to convergence. One example: Starting on March 11, Wall Street’s largest banks, including Goldman Sachs Group Inc. and JPMorgan Chase & Co., must process derivatives trades through clearinghouses, an accomplishment of the 2010 Dodd-Frank financial reform law, itself part of the U.S.’s commitment to convergence. By holding collateral and standing between buyers and sellers, clearinghouses can prevent one participant’s default from infecting all the others. In another step forward, the EU decided in December to create a single bank regulator. 

In Reverse 
But the dream of convergence remains, well, a dream. Conflicting national and regional laws, regulations and accounting standards have blocked the world from getting on the same page on financial reform. This, in turn, has jeopardized the ability of regulators to work across borders to address the next crisis. Shutting down a large failing bank that, say, loses all its capital because of a trading strategy gone haywire isn’t possible without universal rules for resolving sick banks. Moreover, financial companies will be able to take advantage of regulatory arbitrage -- shifting operations to countries with the loosest rules.

What happened? Let’s take a tour.
 In the U.S., regulators have been lobbied to a standstill. They have yet to name a single nonbank financial company or industry as systemically risky, despite the immense size and vital roles played by money-market funds, hedge funds, insurers and nonbank lenders. 
The Commodity Futures Trading Commission is backing away from some of its early positions on derivatives, moves that could have broken the big-bank stranglehold over the swaps business. The agency looks likely to revoke a proposal that would have required large investors to solicit quotes from at least five dealers, as a way to promote pre-trade price transparency. 
Regulatory agencies have also stalled over the Volcker rule, named after former Federal Reserve Chairman Paul A. Volcker. The measure is supposed to limit speculative trading by federally insured banks. For more than a year, five agencies have been debating with large banks and among themselves about where to draw the line between trading and making markets for clients, which the law exempts from the Volcker rule. On Capitol Hill, meanwhile, lawmakers from both parties and both chambers want to repeal parts of Dodd-Frank, including the requirement that banks move derivatives trading to separate affiliates with their own capital. 

Nasty Split
In Europe, the situation is no more auspicious. A nasty split has opened between the Continent and the U.K. The European Parliament and national governments have moved in recent weeks to tax financial transactions and cap bankers’ bonuses. This has (rightly) rubbed the British the wrong way, as their model of finance -- the Anglo-Saxon model -- is less regulated, more centered on trading and pays bigger bonuses than its counterparts in, say, France or Germany. 
Another rift is between Europe and the U.S. -- this one over capital requirements. New rules being written in Basel, Switzerland, have been watered down after much bickering. The level is now set at 7 percent of risk-weighted assets, up from 2 percent. Still, it falls short of the 10 percent initially sought by the U.S., and way short of the 20 percent of total assets that some economists and academics recommend. France and Germany led the opposition, seeking to protect the interests of their biggest lenders, which would have needed to raise more capital than foreign competitors, Bloomberg News has reported. Not only is the global financial system no safer now than it was in 2008, it’s also clear that the project of convergence is badly stalled. Is the world really prepared to let the great convergence turn into the great divergence?" - source Bloomberg.

On a final note the principal reason for banks to hold a larger equity buffer is to be able to face risks such  as real estate bubbles. For instance both Credit Suisse and UBS have been asked to hold more capital to that effect as reported by Bloomberg:
"The 1.2 swiss-franc-to-euro cap and low interest rates have prevented the Swiss National Bank from tightening monetary policy to avert soaring real estate prices. To mitigate the risk of a property bubble, the authorities plan to curb lending growth by requiring banks to hold an extra 1% of capital on residential mortgages, starting 4Q13. UBS and Credit Suisse had 252 billion francs of mortgages outstanding at end-November." - source Bloomberg.


"What we define as a bubble is any kind of debt-fueled asset inflation where the cash flow generated by the asset itself - a rental property, office building, condo - does not cover the debt incurred to buy the asset. So you depend on a greater fool, if you will, to come in and buy at a higher price." - James Chanos 

Stay tuned!

Tuesday, 25 October 2011

Markets update - Credit - Subordinated debt - Love me tender?

"Junk bonds prove there's nothing magical in a Aaa bond rating."

Merton Miller

Debt tender offer:
"When a firm retires all or a portion of its debt securities by making an offer to its debtholders to repurchase a predetermined number of bonds at a specified price and during a set period of time. Firms may use a debt tender offer as a mechanism for capital restructuring or refinancing."

In our post "The European issue of circularity", we discussed recapitalization issues in general, and subordinated Tier 1 bond tender in particular.

As a reminder:
"We know that "access to capital is depending on growth outlooks", a cheaper way for a bank to beef up its Core Tier 1 capital is to buy back at a discount its Hybrid Subordinated perpetual bonds in the secondary market."
We know that in 2009 "the game was for weakly capitalised banks to quietly retire bonds at distressed levels to create/boost Core Tier 1 capital, which was precious as long as they could finance the purchase with term debt."

We also know from this previous post that French bank BPCE tendered their bonds "to further enhance the quality and efficiency of the Company's capital base".

We expected others to follow suit and given the difficulty for the weaker players in the peripheral space to access capital at a reasonable rate, as well as needing to boost their core Tier 1 capital base, it was of no surprise to see Portuguese bank Banco Espirito Santo following French bank BPCE in tendering some of its subordinated debt on the 18th of October, but this time around, we have a debt to equity swap. So, yes, another long post.

But before we go through the nitty-gritty details, it is time for a quick market overview - Source Bloomberg:
Tighter slightly in the morning as per above picture but wider by the end of the day given concerns related to the cancellation of the meeting of European Union Finance ministers on Wednesday.
Itraxx Financial Senior 5 year CDS index increased by 7.5 bps to around 242 bps.
Itraxx Financial Subordinated 5 year CDS index increased by 6 bps to 474 bps. Overall, this month, the market is tighter by 80 bps since the end of last month, as we have seen a slight improvement in the credit markets so far in October in relation to spreads movements.
Itraxx Crossover 5 year CDS index (High Yield) ended up 7 bps wider as well on the day at around 714 bps.

The liquidity picture - source Bloomberg:
Some improvements but ECB overnight deposits are climbing at a faster pace compared to last month.
Flight to quality mode, on a slight hold pattern as indicated by the relationship between Germany Sovereign 5 year CDS and 10 year German government bonds yield slightly above 2% - source Bloomberg:
We started the day at around 2.13% yield and ended up around 2.05% yield.

EFSF bond versus 10 year German and French government bonds, correlation is still there between French bonds and EFSF bonds - source Bloomberg:

Itraxx Financial Senior 5 year CDS index, Eurostoxx and German Bund 10 year bond yield above 2%, Volatility levels - Source Bloomberg:
So, where do we go from there? It all depends on Wednesday European outcome and the can kicking game.

We all know by now we have moved from convergence to divergence in relation to bonds yields - source Bloomberg:

ECB has been stepping in since the 8th of August to support Italian and Spanish bond yields as they are again moving closer to the dangerous 6% yield threshold.

But back to our Subordinated bond tender story for our Portuguese bank.
The need to raise capital will be acute for peripheral countries due to issue of circularity we previously discussed. Given we know by now that access to capital is only open to better quality issuers in the financial space, the current level of financial spreads for weaker issuers, make it impossible for them to access funding at reasonable rates. Survival of the fittest is still the name of the game with the liquidity support provided by the ECB for these weaker players.

Bloomberg - "Savings Wars From Italy to Portugal Drive Bank Costs Higher"
By Charles Penty and Sonia Sirletti:
"The five largest banks in Italy, Spain and Portugal combined have more than 200 billion euros in medium- and long-term debt maturing before 2013, according to data compiled by Bloomberg.
The last time a Portuguese bank tapped wholesale debt markets was in March 2010, while Banco Santander SA’s 1 billion-euro sale of bonds in June was the most recent by a Spanish lender. UniCredit SpA, Italy’s largest bank, paid a record spread for Italian covered bonds in August when it raised 1 billion euros from a sale of 10-year notes that yielded 215 basis points more than the benchmark mid-swap rate.
Banco Espirito said in August that it trimmed lending by 3.1 percent from a year earlier and boosted customer funds by 23 percent to bring its loan to-deposit ratio down to 155 percent from 198 percent a year earlier. A lower loan-to-deposit ratio is a sign the bank is less reliant on sources of funding such as bond sales to fund its business."

Anabela Reis in a Bloomberg article indicated the following:
"Portuguese banks are being squeezed by demands that they boost capital as the government’s effort to reduce the deficit deepens the recession.
Echoing the struggles of their Greek counterparts, Portuguese lenders are unable to tap the financial markets for funds and hobbled by debt-laden state companies. At the same time, international regulators are forcing them to raise capital as they’re dependent on the European Central Bank for funds."

So austerity measures in conjunction with loan book contractions will lead unfortunately to a credit crunch in peripheral countries, seriously putting in jeopardy their economic growth plan and deficit reduction plans.
We discussed our concerns back in August in the post "It's the liquidity stupid...and why it matters again...":
"Lack of funding means that bank will have no choice but to shrink their loan books. If it happens, you will have another credit crunch in weaker European economies, meaning a huge drag on their economic recovery and therefore major challenges for our already struggling politicians.

As a reminder, 50% of banks earnings for average commercial banks come from the loan book: no funding, no loan; no loan, no growth; and; no growth means no earnings."

In a Bloomberg article by Liam Vaughan and Aaron Kirchfeld on the 25th of October -"Italy, Spain May Bear Brunt of European Bank Capital Plan":
"Banks with large holdings of U.K., German and French bonds may avoid raising additional capital, while those with Greek, Irish, Italian, Portuguese and Spanish debt will have to raise the most, according to London-based analysts at JPMorgan Chase and Co. and MF Global Ltd."
Hence the issue of circularity weighting on banks' capital needs.

Liam Vaughan and Aaron Kirchfeld commented:
"In Portugal, Banco Espirito Santo SA, the country’s largest lender by market value, may require about 3.4 billion euros, and Banco Comercial Portugues about 3.9 billion euros, according to MF Global.
Spain’s two largest banks, Banco Santander SA and BBVA may require about 3.1 billion euros each, Banco Popular SA 2.8 billion euros, Banco de Sabadell SA 2 billion euros and Bankinter SA 914 million euros, according to JPMorgan."
We also learn from the same article an interesting point:
"Banks with large holdings of U.K., German and French bonds may avoid raising additional capital, while those with Greek, Irish, Italian, Portuguese and Spanish debt will have to raise the most, according to London-based analysts at JP Morgan and MF Global Ltd."

Reason behind, another interesting accounting trick according to the same article:
"Lenders may be able to mark up the value of bonds that are trading above face value, allowing them to mitigate the cost of writing down their southern European sovereign debt, the people said."
So we have the direct effect of circularity we discussed at play as indicated again by Bloomberg:
"That may benefit U.K. and German lenders such as Royal Bank of Scotland Group Plc and Deutsche Bank AG, whose biggest holdings of bonds are those issued by their own governments. It may also allow French banks to avoid further fundraisings."

And we know from our conversation "Long hope - Short faith", that:
"Banks have fought bitterly against increasing equity buffers which is the cheapest and easiest way to recapitalize banks.

Why? Because allowing high payouts to shareholders, namely bank employees in many cases, allows financial institutions to raise their leverage."

Liam Vaughan and Aaron Kirchfeld in their Bloomberg article indicated the following:
"Lenders including Deutsche Bank have opposed further capital injections because they risk diluting shareholders without addressing the underlying problem of a potential Greek default. BNP Paribas SA, France’s largest bank, is among financial firms that have said they can meet demands for increased capital without cash injections."

So what will happen now and how will these banks raise money to meet capital ratios before the June 2012 deadline?

They will contract their balance sheets, in effect impacting access to credit and triggering most likely another credit crunch and it is already happening.

Source Bloomberg, Anabela Reis - "Portuguese Banks Pinched With Recession Deepening: Euro Credit"
"Loans to companies dropped to 116.2 billion euros in August, the lowest since March, and loans to individuals declined to 140.8 billion euros, the lowest in a year, according to the Bank of Portugal."
So what's all about your Banco Espirito Santo tender Martin?
Well as Espirito Santo Chief Executive Officer Ricardo Salgado put it nicely:
"Its more interesting for banks to extend their shareholder base, by converting bonds into shares, than having the state as a shareholder."
On October 18 Banco Espirito Santo announced a capital increase in effect via its bond tender:
BESPL 6.625 Perp callable 2012 Exchange at 74 Upper Tier 2 XS0147275829 Amount: 423,561,000

BESPL 4.50 Perp callable 2015 Exchange at 66 Upper Tier 2 XS0207754754 Amount: 474,033,000

BESPL 5.58 Perp callable 2014 Exchange at 61 Tier 1 XS0171467854 Amount: 553,265,000

And my good credit friend to comment:
"First debt to equity swap for a Portuguese bank: Banco Espirito Santo … but I guess not the last one for European banks … as we have been saying for a while…
The total amount of debt to be exchange for equities is euro 1,450,859,000 ! Banco Espirito Santo total market cap is approximately euro 1,743 million…which means 83.5% dilution for the current shareholders!"

This is the recent price action on Banco Espirito Santo share price:

So, in our debt to equity swap, courtesy of the subordinated bond tender, not only the subordinated bond holder is taking a hit, but our shareholder as well. Love me tender?

Subordinated debt - Wikipedia:
"From the perspective of policy-makers and regulators, the potential benefit from having banks issue subordinated debt is that the markets and their information-generating capabilities are enrolled in the "supervision" of the financial condition of the banks. This hopefully creates both an early-warning system, like the so-called "canary in the mine," and also an incentive for bank management to act prudently, thus helping to offset the moral hazard that can otherwise exist, especially if banks have limited equity and deposits are insured. This role of subordinated debt has attracted increasing attention from policy analysts in recent years."

But if you think the credit crunch will only happen in the peripheral countries because of banks shrinking their balance sheets, think again:
According to my good quant friend at Macro Research house RCUBE (Risk - Return - Research), and from the latest “Association Française des Trésoriers d’Entreprise” (French Corporate Treasurers Association), the latest survey confirms the reality of a credit crunch in France, respondents now consider that the cash situation for French corporates is nearly as bad as in late 2008! - "Our readers know that we pay very close attention to bank lending standards, especially in Europe where banks represent around 70% of corporate financing."

Europe Banks Vow $1 Trillion Shrinkage as Recapitalization Looms - Bloomberg by Anne-Sylvaine Chassany and Liam Vaughan - October 19:
"European banks, assuring investors they can weather the sovereign debt crisis by selling assets and reducing lending, may not be able to raise money fast enough to prevent government-forced recapitalizations.
Banks in France, the U.K., Ireland, Germany and Spain have announced plans to shrink by about 775 billion euros ($1.06 trillion) in the next two years to reduce short-term funding needs and comply with tougher regulatory capital requirements, according to data compiled by Bloomberg. Morgan Stanley predicts that amount could reach 2 trillion euros across Europe as banks curb lending and sell loans and entire businesses. A lack of buyers and the losses lenders face on loan sales are making those targets unrealistic."

On a final note I leave you with Bloomberg - Chart of the Day - Euro Area Debt Quality Worsens at Record Pace:
"The CHART OF THE DAY shows the average rating for the bloc, calculated by Bloomberg from the assessments of the three main evaluators, has worsened to 3.14, representing the third-best grade, from 2.12 in May 2010 when the European Financial Stability Facility was designed. The measure fell 0.23 point in the previous 15 months. The average is calculated by giving a numerical grade for each grading, where 1 is the highest, and adjusting it for each country’s share of the EFSF guarantee.
Seven of the 17 euro-sharing nations have had their ratings downgraded since the announcement of the facility, which maintains a top grade from Standard & Poor’s, Moody’s Investors Service and Fitch Ratings. As the contagion has spread to banks, prompting governments to work out recapitalization plans, further cuts, mainly for the top-rated countries, may reduce the strength of the fund."

"How few there are who have courage enough to own their faults, or resolution enough to mend them."
Benjamin Franklin

Stay tuned!

Monday, 17 October 2011

Markets update - Credit - Bedtime story and the European issue of circularity

"Nothing is more frequently overlooked than the obvious."
Thomas Temple Hoyne

Volatility again today. We had a better tone in the morning in the European space credit wise, but we were back to flat at the end of the day. Following the G20, everyone expecting in a week's time big resolution coming out of the European summit. They should be bracing themselves for some disappointment.

As per Bloomberg article today by Tony Czuczka and Rainer Buergin:
"German Chancellor Angela Merkel has made it clear that “dreams that are taking hold again now that with this package everything will be solved and everything will be over on Monday won’t be able to be fulfilled,” Steffen Seibert, Merkel’s chief spokesman, said at a briefing in Berlin today. The search for an end to the crisis “surely extends well into next year.” Group of 20 finance ministers and central bankers concluded weekend talks in Paris endorsing parts of Europe’s emerging plan to avoid a Greek default, bolster banks and curb contagion. Providing a week to act, they set the Oct. 23 meeting of European leaders in Brussels as the deadline."

In this post we will have a look again at bank recapitalization, given it is still the ongoing subject, as a follow up on our previous discussion. We will also discuss the issue of circularity. We touched on the subject in our post - "Macro and Markets update - It's the liquidity stupid...and why it matters again..." in relation to European banks liquidity issues:
"The circularity issue weighting on liquidity:
In highly-indebted Euro zone countries, the issue of circularity comes from the high correlation with their sovereign creditworthiness, meaning they are experiencing very high level of stress on their current funding."

So here we go for another long conversation.

But first, a credit overview.
The Itraxx Credit Indices picture today - Source Bloomberg:
While the tone had been much positive at the open, on credit indices with at one point Itraxx Crossover 5 year index (High Yield) tightening by 23 bps, the market closed the day roughly unchanged, as equities moved from the positive territory to negative. German Finance Minister Wolfgang Schaeuble comments weighted heavily on the market by the end of European close.

Enel, Italy's largest power company came to the market with 2014 and 2015, with a new issue premium to secondary of around 50 bps for the 2014 bonds and a new issue premium of 90 bps for the longer tranche.

There was as well some resurgence in news issues in the financial space with an interesting 2 year Senior Unsecured Floating Rate note from Commerzbank, rated (A2/A/A+ outlook : stbl/neg/stbl), which priced at Euribor +158 bps. On the 12th of October SEB (Skandinaviska Enskilda Banken AB - A1 / A / A+) priced a similar note at around Euribor +120 bps.
We know from the post "Markets update - Credit - Misery loves company" that ABN Amro (Aa3 /A/A+ all stable outlook), priced a similar floater on the 30th of September at around Euribor +130 bps, as a follow up on Deutsche bank which priced at around +100 bps.

So no surprise there, new issues are not only repricing the secondary issues, but coming with big concessions given the need for banks to raise capital. It is interesting to note that apart from these 2 year Senior unsecured notes, for some prime issuers, it seems the subordinated market is still completely shut down.

In relation to flight to quality, convergence of German 10 year Government Yield and German Sovereign CDS seems to have stopped in its tracks - Source Bloomberg:
From 2.18% Yield to 2.08% on the 10 Year German Bund.

But the interesting part today was the new record set in terms of spread between the German 10 year Bond and the French 10 year Bond (OAT), which reached 95 bps - Source Bloomberg:
France still in the crosshairs of the European bond vigilantes.

The liquidity picture - Source Bloomberg:
Some improvement but nothing major so far.

And Nomura had a good comment relating to recent market action in their recent Rates Strategy Europe weekly from the 14th of October:
"Convalescence with relapse risk:
Beyond October, we are worried by the possibility of a relapse in market sentiment. There is ample scope for disappointment on the euro plan (see Euro plan: Bazooka or damp squib?). Our take is that the "bazooka" will not happen. But in a risk-on phase partly triggered by better economic sentiment, it would take a really disappointing announcement to immediately derail markets. In July, there was a very incomplete announcement in a very negative market; the background is different this time. So at this stage, we are not necessarily waiting for a major risk off, but we are aware of the risk of relapse in the aftermath. There are several triggers: (1) the PSI will be revisited with tougher terms, paving the way for a possible CDS trigger, (2) the political situation in Greece is very unstable and the Troika returns to Athens no later than end-November (assuming the next tranche is paid, the government has money only until January), and (3) it is not clear how the ECB's bond buying will continue and how the central bank will react to a GGB default (the collateral issue can be by-passed in the event of a temporary selective default; it would be more complicated with a CDS-triggering event)."
Ouch...so much for all the recent European politicians "Bedtime story"...

And Nomura to add relating to the periphery:
"The market has largely shaken off the recent euphoria over possible quick fixes to the Eurozone and sovereign spreads have come under pressure to some extent as a consequence. While many would look for a large scale solution on the horizon, from the possibility of extra IMF funds (possible with many caveats), to large scale recap of banks (obviously not a solution in and of itself), to various insurance schemes (which could come with practical and legal challenges), the likelihood of any single solution arriving imminently appears remote.

Against this backdrop we continue to believe that sovereign spreads that are unsupported by the ECB will come under pressure."

So, unfortunately, no Bazooka to be expected anytime soon.

And that leads us to the issue of circularity we previously mentioned. And, in relation to bank recapitalization, don't expect wizards, fairy tales and magic tricks in our "Bedtime story".
The issue of circularity we mentioned earlier again cannot be clearer than the graph realised by Martin Sibileau in his latest post - "The EU must not recapitalize banks":
oct-17-2011
And as indicated by Martin Sibileau:
"The circular reasoning therefore resides in that the recapitalization of banks by their sovereigns increases the sovereign deficits, lowering the value of their liabilities, generating further losses to the same banks, which would again need more capital."

To illustrate further the issue of circularity, here is a table from Bloomberg displaying Greek debt ownership:
The 6 top owners of Greek debt are 6 Greek banks.

And I have to agree with Martin Sibileau's view:
"What would be a solution for the EU? We have repeatedly said it: Either full fiscal union or monetization of the sovereign debts. Anything in between is an intellectual exercise of dubious utility."

And the clear difference between the ECB and the FED in relation to bond purchases is as follows, as pointed out by Martin Sibileau:
“…The Fed was financing what we call in Economics a “stock”, i.e.( mortgages) “…a variable that is measured at one specific time, and represents a quantity existing at that point in time, which may have accumulated in the past…”
"The ECB is financing “flows”, deficits, or “…a variable that is measured over an interval of time…” Therefore, by definition, we cannot know that variable until the interval of time ends…When will deficits end? Exactly!! Nobody knows! Thus, it is naïve to ask more clarity on this issue from the ECB. The only thing that is clear here is that the Euro, i.e. the liabilities of the ECB will necessarily have to depreciate as long as that interval of time exists, until a clear reduction in the deficits is seen…”
Stock and flows:
"Economics, business, accounting, and related fields often distinguish between quantities that are stocks and those that are flows. These differ in their units of measurement. A stock variable is measured at one specific time, and represents a quantity existing at that point in time (say, December 31, 2004), which may have accumulated in the past. A flow variable is measured over an interval of time. Therefore a flow would be measured per unit of time (say a year). Flow is roughly analogous to rate or speed in this sense."

And following the circularity, let's discuss current recapitalization issues as there were some interesting developments today namely involving subordinated Tier 1 debt.

BPCE, the French bank decided to launch a tender and offered to buy back subordinated bonds as much as 1.8 billion Euros of four subordinated hybrid securities:

Why so? Given we know that "access to capital is depending on growth outlooks", a cheaper way for a bank to beef up its Core Tier 1 capital is to buy back at a discount its Hybrid Subordinated perpetual bonds in the secondary market.

We discussed this very subject in the post "Markets update - Credit - Crash Test for Dummies":
"In 2009, the game was for weakly capitalised banks to quietly retire bonds at distressed levels to create/boost Core Tier 1 capital, which was precious as long as they could finance the purchase with term debt.

If a financial entity is able to buy back its LT2 debt below par, it generates earnings (the beauty of FAS 159, on that subject see my post "Statement 159 - Debt Valuation Adjustments - Déjà Vu 2008.") and then Core Tier 1 capital. It's a kind of magic...because this way a bank's total capital base goes down (by retiring LT2 debt) and given regulators care most about the Core Tier 1 ratio, everyone is happy (probably note the subordinate bondholder)."

and bingo! French bank BPCE strikes today!

And a market maker to comment following the BPCE tender:
"Very big moves in T1 space mainly driven by BPCE T1 tender which came approximately 13 points above secondary (for the low coupons bonds). The market rapidly drew the conclusion that similar moves would be coming on in French names - with a particular focus on low-cash, step-up bonds."

BPCE Tier 1 subordinated perpetual bonds indicative round up:
BPCEGP 4.625% 07/15 (call date) cash price - 61/64 +13.75 points
BPCEGP 5.25% 07/14 (call date) cash price - 62/65 +11 points
BPCEGP 6.117% 10/17 (call date) cash price 61/64 +9 points
BPCEGP 9% 03/15 (call date) cash price 78/80 +4 points
BPCE 9.25% 04/15 (call date) cash price 76/79 -

BPCEGP 5.25% 07/14 (call date) - Source Bloomberg

BPCE commented on its tender:
"The Tender Offer is being undertaken in order to further enhance the quality and efficiency of the Company's capital base."
Of course it is!

On a side note, FAS 159 is fashionable again in the banking space:
DVA/CVA in earnings:
UBS = 1.6 billion USD
JP Morgan = 1.9 billion USD
Citi = 1.9 billion USD
To be continued...(Bank of America, Goldman Sachs, Morgan Stanley, etc.).

And on a final note I leave you with Bloomberg chart of the day, showing that Asian stocks are yet to reach bear-market floors:
According to Bloomberg:
"Stocks in Asia excluding Japan may extend a bear-market rally for “several” weeks before resuming declines that could send them to new lows next year, according to Mizuho Securities Asia Ltd. The MSCI All Country Asia excluding Japan Index rebounded 13 percent in the six days through Oct. 13, following a 31 percent plunge from its April 28 intraday high. In the four previous periods when the Asian gauge dropped more than 30 percent from peak to trough closing levels since records began in 1988, all were interrupted by rallies of between 14 and 45 percent, before the routs resumed. A minimum drop of 20 percent from a peak signals to some investors a bear market."

"There cannot be a crisis next week. My schedule is already full."
Henry A. Kissinger

Stay tuned!

Monday, 12 September 2011

Markets update - Credit - Crash Test for Dummies


I had previously extended an invite for next post title, given one of the reader had already used my previous analogy relating to the "Chandrasekhar limit", but I have not received a suggestion yet. I felt the urge of posting an update after another eventful session today.

All credit indices went through the roof, once again:
Itraxx Crossover 5 year index (European High Yield - 40 companies in the index):
Risk of contagion is truly on, and Greece is drifting wider still, with two years notes yielding more than 60%.
For Greece, we already know the score with the central government's budget gap hitting 22% in the first eight months. The Greek goverment is now expecting the economy to contract by more than 5% in 2011, more than the 3.8% forecast by the European commission.

Here is the picture for Greece today:
Greek Yield one 1 year government bond - 117% yield:

Greek 2 year bonds yielding 63.4%:

Greek 10 year bonds, 21.87% yield:

Greece's fate is signed, sealed and delivered.

What caught my attention today was Italy's auction on T-bills with yields hitting a new three year record at above 4.153% from 2.959% a month ago. Contagion is still on.

And liquidity indicators were still worsening today,

But the deterioration seems to be accelerating still as the Euro-USD Basis swap 3 months indicator is telling us:

Banks have now 181 billions euros of deposits parked at the ECB, up from 152 billions when I wrote "Markets update - Credit - Crossing An Event Horizon" on the 5th of September:

So yes, flight to quality it is, and flight to quality we have. Correlation between 10 year Swedish government bonds and 10 year German government bonds is 1:

And financials, both in the equity space and in the credit space, took the brunt of the sell-off / widening today:
Itraxx Financial Senior 5 year index flying through 300 bps:

Itraxx Financial Subordinated 5 year index, widening faster:
This movement in credit indices was summarised by a dealer today as following. We had capitulation in the Financial Subordinate space and in relation to Financial Senior, the widening was strong but not sustained by flows. Size for hybrid Tier 1 trades was around 1 million euros, with significant downwards movement, 10 points down. In relation to High Yield volumes, they are very light. Whereas CDS so far had been leading the widening move, in last couple of days, cash has been underperforming CDS today.

In relation to bank capital structure, it is important at this juncture to go through the architecture, from the most senior to least subordinated bank debt.
Covered bonds backed by prime pool of loans are deemed senior to Senior debt.
Below senior debt, you have subordinated debt:
Lower tier 2 (LT2), Upper tier 2 (UT2), Tier 1 debt and finally equity (preferred shares).


And we know by now that European and UK banks face more funding pressures than US banks:


Typically, in subordinated CDS single names, the bond reference is a Lower Tier 2 bond (LT2), and not Tier 1 (T1) bonds or Upper Tier 2 bonds (UT2), as coupon payments can be deffered in these structures. For Tier 1 bonds and UT2, missing a coupon does not constitute a credit event, therefore they cannot be used as a reference for a single name financial subordinate CDS, so no CDS on these bonds.

A typical LT2 Structure is as follows:
10 years, non-callable for 5 years (10-NC5)
-Final maturity is hard, meaning no get out clauses.
-No coupon deferral. A coupon deferral would constitute a credit event and therefore trigger a credit event and the relating CDS.
-Ratings: 1 notch below senior debt (Moody's / S&P).
-More standardised structure than Tier 1 or UT2. Given regulatory capital treatment decreases as it moves towards maturity (as it gets closer to 5 years to maturity) so many deals structured have had callable features, meaning the issuer can decide to call the bond.

Why am I going through these details relating to Bank Capital structure? Simply because mister Market "sometimes" has a short memory span. On the 17th of December 2008, Deutsche Bank decided to skip the call option on a 1 billion euro LT2 bond. Not so good for their reputational risk at the time.

In 2009, the game was for weakly capitalised banks to quietly retire bonds at distressed levels to create/boost Core Tier 1 capital, which was precious as long as they could finance the purchase with term debt.

The big issue today is that we know from previous credit posts that they cannot at the moment issue term debt given current market dislocation and the only bonds which, so far have been issued, have been the most senior ones, namely covered bonds backed by pools of prime loans but by only for top issuers.

If a financial entity is able to buy back its LT2 debt below par, it generates earnings (the beauty of FAS 159, on that subject see my post "Statement 159 - Debt Valuation Adjustments - Déjà Vu 2008.") and then Core Tier 1 capital. It's a kind of magic...because this way a bank's total capital base goes down (by retiring LT2 debt) and given regulators care most about the Core Tier 1 ratio, everyone is happy (probably note the subordinate bondholder).

But, it is clear that not all banks have the same liquidity/funding costs, particularly today. So the game is going, once again to be as follows, remember: "The recent significant increase in credit spreads for many financials have been driven by the markets concerned about the ability of the weaker players to access credit at reasonable rates." (Macro and Markets update - It's the liquidity stupid...and why it matters again... ), banks with access to cheaper senior term funding than the cost of their outstanding LT2, for them, an early call could make sense, compared to the cost of issuing senior debt. For the others, I am not so sure...

Survival of the fittest.

And is this fully priced in the subordinate space? I don't think so, given borrowers are expected generally to repay subordinated bondholders at the first opportunity and the bonds are valued on that basis.

So, dear credit friends, I am afraid to say that, skipping calls, are going to happen, and will trigger losses because end of the day, why would you call a bond, if it costs you more to issue a new one?

This time is different? Nope. It is still deleveraging.

And my good credit friend agrees on the above, I am not alone:
"Do not forget that in 2008, when funding became an issue (and it is becoming an issue right now) Deutsche Bank decided not to call a LT2 bond at its call date, and all participants suddenly woke up to the reality that subordinated bonds could not be called.

Needless to say that it could and …… should happen again."

And given UK banks have just been given the ICB slap, recommending on ring-fencing retail banking and increasing loss absorbency, meaning lower ratings (downgrades), lower profitability and higher funding costs, this might bring some solace to their French counterparts (Moody's fear of downgrades), which recently have been at the receiving end of the cricket/baseball bat, you can expect additional widening unfortunately.
[Graph Name]

Until next time, I give you Bloomberg Chart of the Day, pointing towards additional pressure on the Euro:

Stay tuned!

 
View My Stats